Water damage insurance in Fort Lauderdale: what usually applies
By Lauderdale Flood Line · Updated
The short version
It turns on where the water came from. Sudden leaks inside the home usually fall under homeowners or condo unit-owner coverage; water that rose from the street, a canal or a king tide needs a flood policy. Florida law adds its own deadlines and rules, listed below with links to each statute.
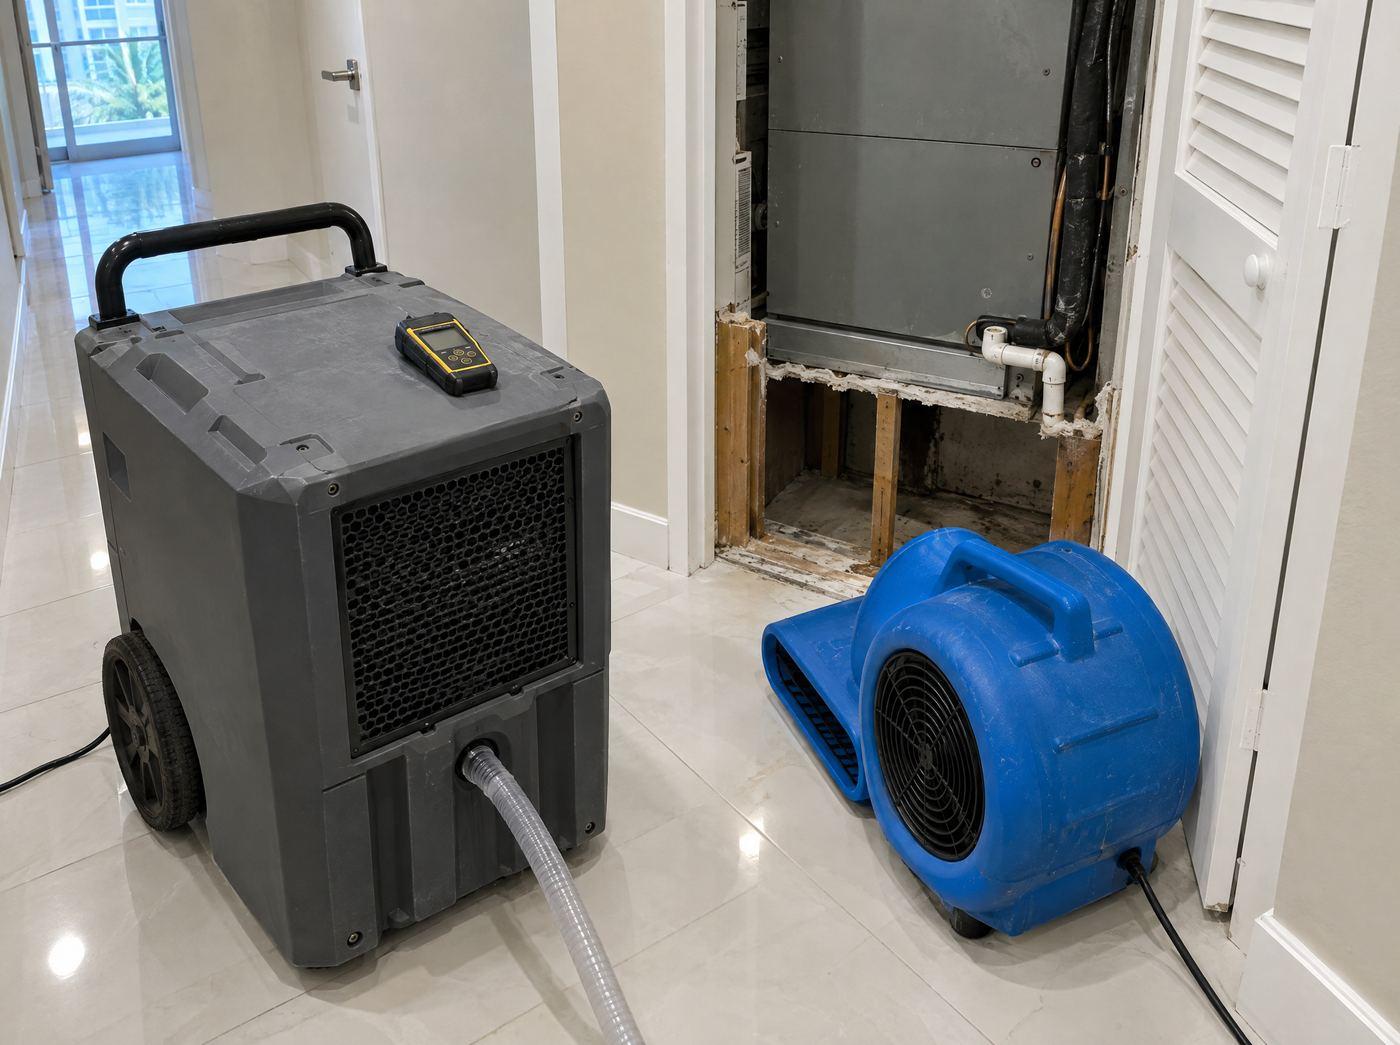
Illustrative photo.
This page explains coverage; it doesn't tell you whether to involve your insurer, and Lauderdale Flood Line has no part in any claim. We are a referral line, and how we are paid never depends on insurance.
Which coverage usually applies?
Pick the cause closest to yours.
Usually homeowners (or condo unit-owner) coverage
Water that escapes suddenly from plumbing, an appliance or the AC is the kind of water loss a standard homeowners form is written around, after your deductible.
What it usually involves
- Removing the water and drying the structure
- Opening walls or floors needed to dry them
- Putting finishes back once they're dry
Watch for
- The failed part itself (the pipe, the heater, the drain pan) is usually a separate repair
- In a condo, items inside the unit such as water heaters and appliances fall to the unit owner (718.111(11)(f))
General information, not insurance advice. Your policy and declarations page decide.
What's different in Fort Lauderdale
- Flood exposure is common here. The city says a majority of its residents live in or close to a Special Flood Hazard Area, and you can check one address on the city's flood zone lookup or call the floodplain manager at (954) 828-6133.
- King tides are flood water, not a leak. The city's king tide page lists at least 40 predicted king tide days in 2026.
- FEMA's records show 7,976 NFIP claims in the city's ten residential ZIP codes, with $242,706,124 paid (calculated by Lauderdale Flood Line on November 12, 2026; by ZIP here).
- The city's water property stops at the meter, so a leak on your side is yours to repair. Breaks on the street side go to (954) 828-8000.
- In a condominium, the association's policy and each owner's policy split the building between them (section 718.111).
Florida rules at a glance
Short summaries; follow each link for the statute's exact words (2026 Florida Statutes).
- Notice of a new or reopened property claim is due within 1 year of the date of loss; a supplemental claim within 18 months. Fla. Stat. 627.70132
- Insurers must acknowledge your communication within 7 days, inspect within 30 days of proof of loss, and pay or deny within 60 days of notice. Fla. Stat. 627.70131
- For policies issued on or after January 1, 2023, assigning post-loss benefits to a contractor is void. Fla. Stat. 627.7152(13)
- Hurricane deductible options of $500, 2, 5 and 10 percent must be offered, and the deductible applies once per calendar year. Fla. Stat. 627.701
- Citizens policyholders must carry flood insurance on a schedule that reaches all remaining personal residential policies on January 1, 2027 (condo unit-owner forms and wind-excluded policies are exempt). Fla. Stat. 627.351(6)(aa)
- The state's property insurance mediation program is paid for by the insurer; disputes under $500 are excluded. Fla. Stat. 627.7015
- Only licensed public adjusters or attorneys may be paid to negotiate a claim for you; public adjuster fees are capped at 10 percent after a declared emergency and 20 percent otherwise. Fla. Stat. 626.854
- Contractors may not advise you on coverage or adjust a claim without a public adjuster license, and must give a good faith estimate with any repair agreement. Fla. Stat. 489.147
- In a condominium, the association's policy excludes floor, wall and ceiling coverings, appliances, water heaters and built-in cabinets inside the unit. Fla. Stat. 718.111(11)(f)
What we will never do
- Ask you to file a claim, or offer anything for filing one.
- Negotiate with your insurer or tell you what your policy covers.
- Say that any company you reach is licensed or insured. Check that yourself on the state license search before work starts.
If you and your insurer disagree later, Florida runs a property insurance mediation program that the insurer pays for (section 627.7015). For your water problem itself, see the pipe and water heater, AC leak and flood and king tide pages.
Questions people ask
Does homeowners insurance cover king tide flooding in Fort Lauderdale?
No. Tide and street water that rises from outside is flood damage, which standard homeowners policies exclude. Only an NFIP or private flood policy covers it, and the City of Fort Lauderdale notes a 30-day wait before new NFIP coverage takes effect.
Who covers a leak inside my Fort Lauderdale condo?
Florida Statutes section 718.111(11)(f) says the association's property policy excludes floor, wall and ceiling coverings, appliances, water heaters, water filters and built-in cabinets inside each unit. Those are the unit owner's, so a unit-owner policy is what usually responds for them.
How long do I have to give notice of a property loss in Florida?
Section 627.70132 bars a claim unless notice is given within 1 year after the date of loss, and a supplemental claim within 18 months. The statute is linked below; your policy may set its own steps.
Can the restoration company handle my insurance for me?
Not as your representative. Florida bars contractors from interpreting a policy or adjusting a claim without a public adjuster license (section 489.147), and only licensed public adjusters or attorneys may be paid to negotiate for you (section 626.854). A company can share its photos, moisture readings and itemized estimate with you.